Assessment
Synctera is used by fintechs and banks that need a banking-as-a-service layer for accounts, cards, and money movement. In March 2025 it raised $15M and signed Bolt as its largest customer, and its best use cases are fintech bank accounts, debit and credit cards, and compliant sponsor-bank programs. Prices are quote-based, and its main competitors are Treasury Prime, Unit, and Column.
Peter Hazlehurst co-founded Synctera and is its chief executive. The 2025 round took total equity raised to $94M. The company also offers compliance testing tools for banks and fintechs and has expanded into Canada.
It fits a fintech that wants a managed path to sponsor banks with shared compliance tooling. It is a weaker fit for a company that only needs a simple business checking account, and for a buyer that wants posted prices on the website.
Rating by criterion
We score each of the eight criteria out of 100.
Sector criteria
Launch accounts and wallets through sponsor banks. Synctera’s platform is built for fintech deposit products.
Add debit or credit cards on the same stack. Card issuing is a core product path beside accounts and money movement.
Use its compliance tooling. Cable and related products help banks and fintechs test and monitor compliance.
Connect bank and fintech partners. Synctera markets itself as the orchestration layer between both sides.
Vendor criteria
Expect continued platform work. The 2025 capital and Bolt win point to larger embedded-banking programs.
Budget time for bank partnership setup. BaaS launches still need sponsor-bank and compliance work.
Ask for pricing by product. Public pages do not post a full fee schedule.
Negotiate program scope. Larger programs have more leverage on fees and service levels.
Against its peers
These are the other companies in business banking and treasury, with their ratings.
User comments
We read Synctera’s March 2025 funding coverage and about page to see what buyers value, and set them against the main limit a buyer meets.
- Upside
- Downside
Where customer reviews couldn't be found, our analysts attempted to give a voice to buyer sentiment, drawing on real information from review sites, forums and product documentation.
Based on: TechCrunch, March 2025; Synctera, about.
Fact file
| Chief executive | Peter Hazlehurst, co-founder |
|---|---|
| Founded | 2020 |
| Total equity raised | About $94M |
| 2025 round | $15M extension |
| Largest customer | Bolt |
| Markets | US and Canada |
Competitive landscape
Banking-as-a-service platforms a fintech would compare with Synctera.
Synctera: 76
- Synctera76
- Modulr77
- Increase77
- Treasury Prime73
- UnitNot reviewed
Increase gives fintechs direct banking APIs for accounts and US payment rails, including FedNow and RTP, with sales-led pricing like Synctera.
Comparisons
Key leadership
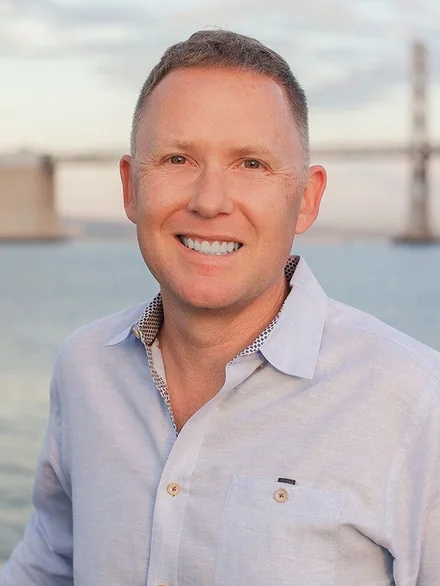
Peter Hazlehurst co-founded Synctera and is its chief executive.
How this review was created
This profile gives our own assessment of Synctera to companies selecting a Business banking & treasury provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Synctera gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, public reviews and filings. Fact-checking took place on November 5, 2026.
Source pages
- Synctera home page: https://www.synctera.com/ (As of November 5, 2026)
- Synctera, about: https://www.synctera.com/about (As of November 5, 2026)
- Synctera, funding news: https://www.synctera.com/news/banking-as-a-service-leader-synctera-raises-15m-and-signs-bolt-its-largest-customer-to-date (As of November 5, 2026)
- TechCrunch, March 2025: https://techcrunch.com/2025/03/11/baas-startup-synctera-raises-15m-signs-bolt-as-a-customer/ (As of November 5, 2026)