Assessment
Moss gives a finance team corporate cards, an inbox for supplier invoices, expense reimbursements and approvals, then pre-books each item for the accounting system. Use it when month-end close is slowed by receipts and invoices arriving in different places. Pricing is a platform fee by module plus a variable fee on volume, with no per-user charge.
Moss was founded in Berlin, Germany, in 2019. Its group company Moss GmbH is an e-money institution licensed by BaFin and a direct member of the Mastercard network, and it keeps customer funds in escrow accounts at Deutsche Bank. More than 7,500 businesses use it, including Pizza Pilgrims and SNOCKS, and Finanz-Szene reported in January 2025 that revenue had reached ~$32M.
It fits a growing company in Europe that wants finance workflows automated and accounting codes applied before month-end. It is a weaker fit for a business that needs a full bank account with lending, or for a sole trader.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
Businesses load a Moss wallet held with Deutsche Bank and pay invoices and reimbursements by bank transfer, in euros or other currencies, through Pay with Moss. Moss is not a bank, so the main business account stays with a bank.
Physical and virtual Mastercard cards come with limits, budgets and approvals, and Moss issues them itself as a direct Mastercard member.
Receipts, invoices and reimbursements are matched and pre-booked with accounting codes, and payment runs can be prepared in the app. Procurement requests and budget tracking sit in the same place.
Moss syncs both ways with DATEV and NetSuite and has more than 40 integrations, including HR systems, so staff changes flow into card and approval settings.
Vendor criteria
Moss has grown from cards into accounts payable, procurement, treasury and AI pre-accounting, and reported 100% ARR growth and 120% net revenue retention in the year to June 2024.
Onboarding runs through a demo and setup with the finance team. Plan time for mapping accounting codes before the first close.
Pricing is a module platform fee plus a variable volume fee with no per-user charges, but amounts are not published. Request a quote for the modules needed.
Contract terms are not public. Ask about the minimum term and how wallet funds are returned on exit.
Against its peers
These are the other companies in business banking and treasury, with their ratings.
Fact file
| Regulator | BaFin, e-money institution (Moss GmbH) |
|---|---|
| Card network | Direct Mastercard member and card issuer |
| Customers | More than 7,500 businesses |
| Revenue | ~$32M, reported by Finanz-Szene in January 2025 |
| Pricing model | Module platform fee plus volume fee, no per-user fees |
Competitive landscape
Spend-management and corporate-card providers a European finance team would compare with Moss.
Moss: 77
Comparisons
Key leadership
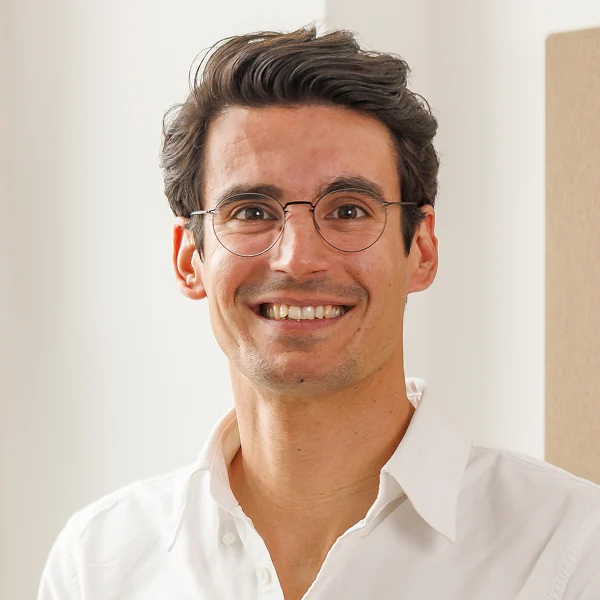
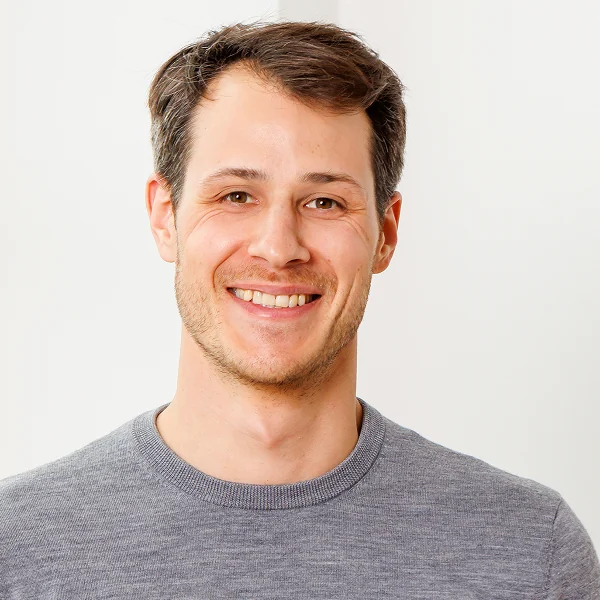
Ante Spittler co-founded Moss in 2019 and is chief executive. Stephan Haslebacher, also a co-founder, is chief operating officer.
How this review was created
This profile gives our own assessment of Moss to companies selecting a Business banking & treasury provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Moss gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, and filings. Fact-checking took place on October 22, 2026.