Assessment
Pave is used by lenders that underwrite cash advances, small-dollar loans, personal loans, and cards with bank transaction data. It reports crossing 100 million monthly credit risk evaluations in early 2026, and its best use cases are continuous risk scoring after origination, approval expansion, and portfolio monitoring. Prices are quote-led, and its main competitors are Zest AI, Taktile, and Nova Credit.
Raymond Rouf is co-founder and chief executive; Ema Rouf is co-founder and president. The company markets AI-powered cashflow analytics built on large transaction and outcome networks.
It fits a lender whose edge is cashflow underwriting. It is a weaker fit for a bank that only wants a generic workflow tool with no cashflow models, and for a buyer that needs full loan servicing as the primary product.
Rating by criterion
We score each of the eight criteria out of 100.
Sector criteria
Score borrowers with cashflow attributes built from transaction data. Pave’s core product is cashflow analytics for credit risk.
Use product-specific scores for cash advances, small-dollar loans, personal loans, and cards.
Monitor risk after origination. Pave emphasizes continuous evaluation across the account lifecycle.
Integrate scores and attributes into existing risk models and data warehouses, including Snowflake workflows marketed on the site.
Vendor criteria
Expect model and score expansion as monthly evaluation volume grows past 100 million.
Plan a data and risk-team integration. This is not a one-click consumer loan app.
Ask for pricing by volume and score package. Public pages do not post a full rate card.
Negotiate on data scope and SLA. Lenders with large monthly decision volume have more leverage.
Against its peers
These are the other companies in lending and credit infrastructure, with their ratings.
User comments
Buyer-oriented points below are drawn from Pave’s home page, about page, and February 2026 product post.
- Upside
- Upside
- Downside
Where customer reviews couldn't be found, our analysts attempted to give a voice to buyer sentiment, drawing on real information from review sites, forums and product documentation. We omit sites where vendors pay to be featured or pay for a review, plus any review the site flags as incentivized.
Based on: Pave home page; Pave, 100 million evaluations post; Hoxton Ventures, Pave.
Fact file
| Co-founder and CEO | Raymond Rouf |
|---|---|
| Co-founder and president | Ema Rouf |
| Monthly evaluations | More than 100 million (early 2026) |
| Focus | Cashflow attributes and scores |
| HQ | Los Altos, California |
Competitive landscape
Credit decisioning and cashflow underwriting vendors a lender would compare with Pave.
Pave: 77
Comparisons
Key leadership
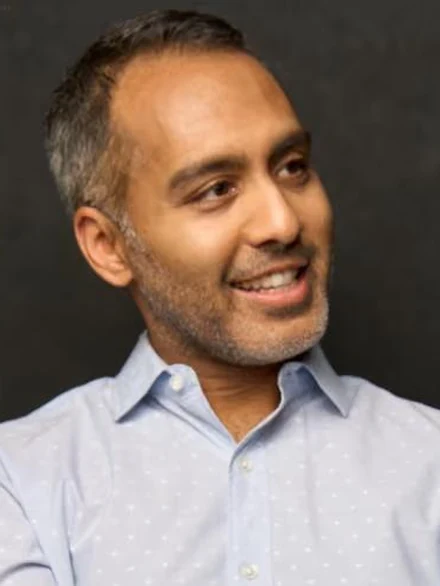
Raymond Rouf co-founded Pave with Ema Rouf and is its chief executive.
How this review was created
This profile gives our own assessment of Pave to companies selecting a Lending & credit infrastructure provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Pave gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, public reviews and filings. Fact-checking took place on November 6, 2026.
Source pages
- Pave home page: https://www.pavefi.com/ (As of November 6, 2026)
- Pave, about: https://www.pavefi.com/about (As of November 6, 2026)
- Pave, 100 million evaluations post: https://www.pavefi.com/blog/100-million-monthly-credit-pulls-why-risk-evaluation-has-moved-beyond-origination (As of November 6, 2026)
- Hoxton Ventures, Pave: https://hoxtonventures.com/portfolio/pave-financial/ (As of November 6, 2026)