Assessment
Earlypay lends against a business’s unpaid invoices and can also fund equipment purchases. It suits an owner whose customers take a long time to pay and who wants a credit facility that grows as the invoice book grows, or a business buying trucks and heavy machinery without draining its cash. The company says funds can arrive in as little as one business day after approval.
For the year ended 30 June 2026, Earlypay reported net revenue of A$36.0 million (up 7%) and results coverage put total revenue near A$52.9 million. Average funds in use, the money it had lent out, were about A$269 million, and the figure ended June near A$308 million. Underlying net profit after tax (NPAT) was A$3.7 million, below the company's earlier hopes, after higher equipment-finance credit costs and a softer first half in invoice finance. Management said the move to a new invoice-finance system finished in August 2026 and guided to stronger FY27 earnings.
Earlypay fits an Australian SME that invoices other businesses and wants a dedicated invoice-finance or equipment-finance provider. It is a weaker fit for a consumer, for a business that only needs pay-later at a marketplace checkout, or for a firm that only wants a small one-off advance with no ongoing facility.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
Earlypay's core products are invoice finance (including confidential invoice finance for larger SMEs, where the business's customers are not told), trade finance, and equipment finance. Facilities can run from tens of thousands of dollars into the millions, and third-party lender summaries cite invoice-finance limits from about A$50,000 to A$10 million. Invoice finance usually does not need property as security, because the unpaid invoices secure the facility. Earlypay assesses the credit of each business and of the customers who owe it money.
Earlypay markets fast access after approval, including funds in as little as one business day. It sells directly and through a growing network of finance brokers. In FY26 it invested in products, new regions, and a single new loan-management system for invoice finance.
Invoice finance is repaid as customers pay the invoices that secure the facility, so there are no fixed monthly loan repayments. Credit costs in equipment finance rose in FY26 as loss rates returned to more normal levels. Confidential facilities suit larger SMEs that do not want their customers told about the financing.
Earlypay finished moving invoice finance onto its new system in August 2026 and says it uses AI tools in its own software development. Its marketing names fewer accounting-software integrations than some fintech competitors do.
Vendor criteria
Earlypay broadened confidential invoice finance, refreshed risk-based pricing, and refocused equipment finance on capital raising, mid-term refinancing, and new or used assets. Its FY27 outlook rests on the larger loan book it held in June 2026 and on the finished systems work. Earlypay is stronger in traditional small-business credit than in lending built into marketplaces or software.
Applications start online, and the company stresses that customers speak with real people. The time from application to first drawdown depends on the credit assessment and paperwork. The corporate site lists support contacts for investors and customers.
Earlypay publishes few of its fees. A third-party lender directory, Business Loan Store, lists indicative invoice-finance interest of 7.99%-13.95% p.a. attributed to Earlypay (figures dated 23 Sep 2026), with drawdown or other fees possible. Earlypay itself says each business gets individual, risk-based pricing, so the actual rate comes from its quote.
Invoice finance terms depend on the facility limit, the advance rate, whether customers are told about the financing, and where customer payments are sent. Equipment finance has its own term and security package. Earlypay does not publish early exit costs, minimum terms, or what happens if funds in use drop in a quiet season.
Against its peers
These are the other companies in lending and credit infrastructure, with their ratings.
Fact file
| Exchange | ASX: EPY |
|---|---|
| FY26 net revenue | A$36.0 million |
| FY26 total revenue (coverage) | About A$52.9 million |
| FY26 average funds in use | About A$269 million; June end about A$308 million |
| FY26 underlying NPAT | A$3.7 million |
| Products | Invoice finance, trade finance, equipment finance |
| Geography | Australia |
Competitive landscape
Peers a buyer would compare.
Earlypay: 73
- Earlypay73
- Butn74
- Scottish Pacific (ScotPac)Not reviewed
- Other AU non-bank invoice / asset lendersNot reviewed
- Major bank debtor financeNot reviewed
Comparisons
Key leadership
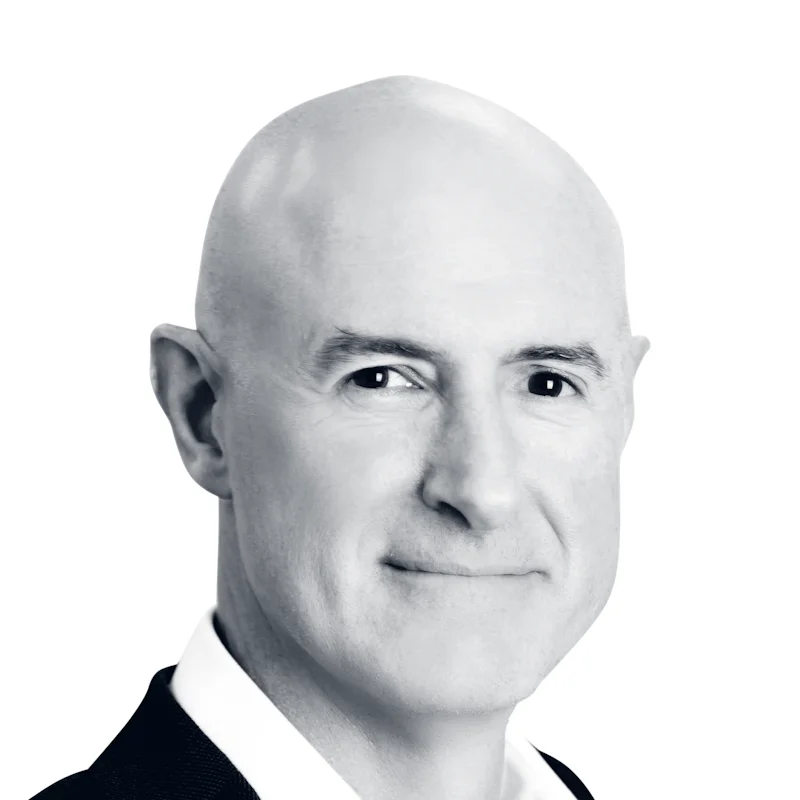 James Beeson
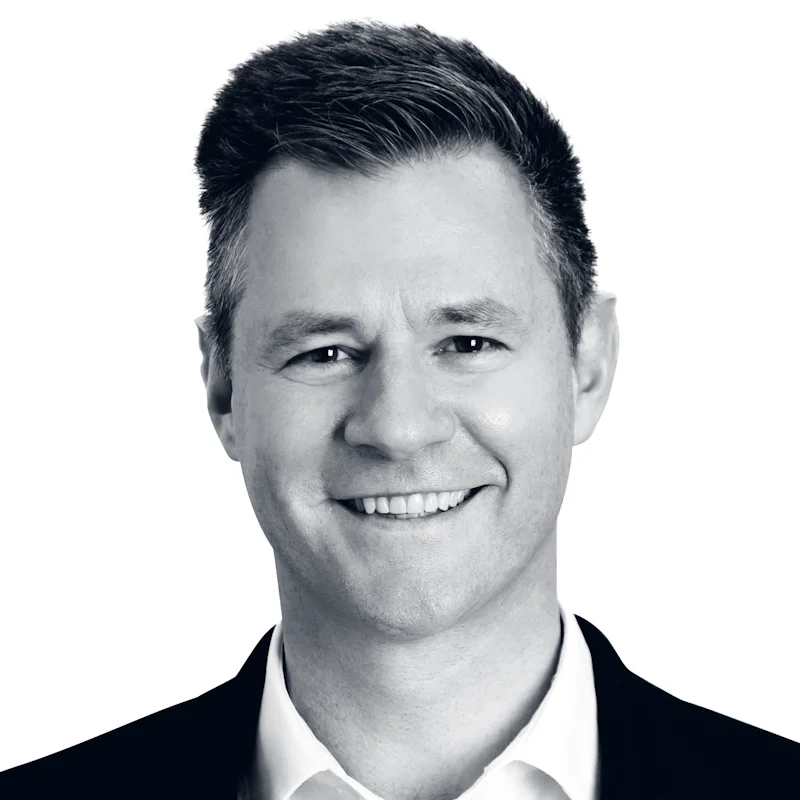 Paul Murray
James Beeson runs Earlypay as chief executive and managing director, and recent results materials list Paul Murray as CFO and COO.
Beeson is known for leading Earlypay’s growth after its rebrand. He joined when Earlypay bought Skippr in 2020. Skippr was an Australian SME finance business where he was CEO and a major shareholder. Earlier he held senior markets roles, including Managing Director and Head of EMEA Rates & Foreign Exchange in J.P. Morgan’s Chief Investment Office, and before that he worked at the hedge fund Brevan Howard and at Citigroup. He became Earlypay CEO in October 2022 after time as COO and chief commercial officer.
Murray is listed as CFO and COO on FY26 results presentations and releases, where he covers finance and operations alongside Beeson.