Assessment
Highnote is used by vertical software companies, B2B platforms, fintechs, and large brands that want to put their own cards in front of customers or staff. Its best use cases are commercial and spend cards, fleet, accounts payable and bill pay, branded credit, and disbursements, and since January 2025 it also processes card acceptance, so one company can both issue and accept cards on the same platform and ledger. On price it competes in the custom-quote tier with Marqeta and Lithic for issuing, while its acquiring rate of 2.85% plus 25 cents is posted publicly. Its main competitors are Marqeta, Lithic, Stripe Issuing, and SoFi Technology Solutions.
The company was founded in 2020; co-founder and chief executive John MacIlwaine earlier led technology at Braintree and LendingClub. Its January 2025 Series B valued it at more than $750 million. Highnote had raised more than $145 million by that round and later added $25 million from existing investors. The platform combines a GraphQL API, a real-time ledger, a secure card data vault, a servicing dashboard, and simulations of any flow before launch, with money movement over ACH, wires, RTP, FedNow, push to card, and stablecoins.
It fits a US company that wants issuing and acquiring from one vendor and expects to add credit or new card products over time. It is a weaker fit for a program that needs issuing across many countries today, and for a very small launch that wants a fixed self-serve price for issuing.
Rating by criterion
We score each of the eight criteria out of 100.
Sector criteria
Issue debit, prepaid, credit, charge, and virtual cards, and accept card payments online, on one platform and ledger.
Build against a full-featured GraphQL API with SDKs, webhooks, an API explorer, and a dashboard that can simulate any flow.
Store card data in the Highnote Vault and run a PCI-compliant stack with team roles and permissions.
Connect external bank accounts through Plaid and move money over ACH, wires, RTP, FedNow, push to card, and stablecoins.
Vendor criteria
Expect steady expansion: acquiring arrived in 2025, followed by credit programs and newer rails such as stablecoin settlement.
Work with a dedicated program manager on issuing launches, with migration support for programs moving from another processor.
See posted acquiring pricing of 2.85% plus 25 cents; issuing pricing is a custom quote with volume discounts and interchange splits.
Negotiate issuing terms by quote; standard acquiring is pay as you go with no setup fee published.
Against its peers
These are the other companies in payments and acquiring, with their ratings.
User comments
These buyer-oriented points draw on Highnote’s pricing and product pages and on coverage of its funding and acquiring launch.
- Upside
- Upside
- Downside
Where customer reviews couldn't be found, our analysts attempted to give a voice to buyer sentiment, drawing on real information from review sites, forums and product documentation. We omit sites where vendors pay to be featured or pay for a review, plus any review the site flags as incentivized.
Based on: Highnote pricing; Highnote about page; Highnote Series B announcement.
Fact file
| Chief executive | John MacIlwaine (co-founder) |
|---|---|
| Founded | 2020, San Francisco |
| Products | Issuing, acquiring, credit, ledger, and money movement |
| Acquiring price | 2.85% + 25 cents per transaction (standard plan) |
| Last priced round | More than $750M valuation, January 2025 |
Competitive landscape
Card issuing platforms and processors a US fintech or software company would compare with Highnote.
Highnote: 77
- Highnote77
- Lithic79
- SoFi Technology Solutions76
- i2c75
- Marqeta74
- Episode Six73
- Stripe IssuingNot reviewed
Comparisons
Key leadership
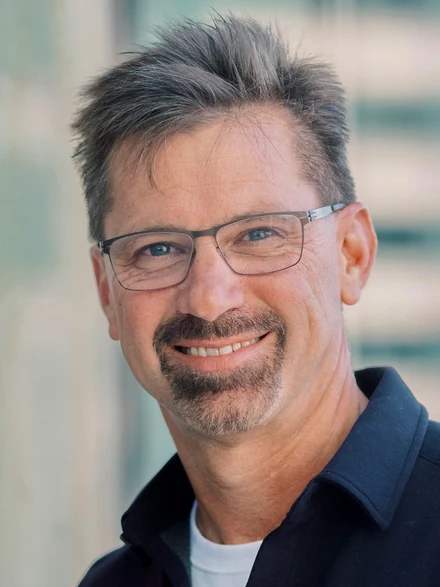
John MacIlwaine co-founded Highnote and is chief executive. He earlier led technology at Braintree and LendingClub and was chief information officer of Green Dot.
How this review was created
This profile gives our own assessment of Highnote to companies selecting a Payments & acquiring provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Highnote gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, public reviews and filings. Fact-checking took place on November 10, 2026.
Source pages
- Highnote about page: https://highnote.com/about (As of November 10, 2026)
- Highnote pricing: https://highnote.com/pricing (As of November 10, 2026)
- Highnote Series B announcement: https://highnote.com/blog/highnotes-dollar90m-series-b-and-expansion-into-us-merchant-acquiring-our-next-phase-of-innovation (As of November 10, 2026)
- Highnote Forbes Fintech 50 announcement, February 2026: https://highnote.com/blog/highnote-named-to-forbes-fintech-50-for-second-consecutive-year (As of November 10, 2026)
- Forbes, January 2025: https://www.forbes.com/sites/stephenpastis/2025/01/21/fintech-payments-startup-highnote-hits-750-million-plus-valuation/ (As of November 10, 2026)
- FinSMEs, January 2025: https://www.finsmes.com/2025/01/highnote-raises-90m-series-b.html (As of November 10, 2026)