Assessment
Thredd sits between the card network and the card issuer. It authorises each transaction in real time, keeps card and account records, and handles settlement and tokens for debit, prepaid and credit programmes. Use it when a fintech or bank wants to issue cards without running its own processing, and may want to make approval decisions itself.
The company started in 2007 as Global Processing Services and now trades as Thredd from London, England, with growth in Asia-Pacific and a US product line. Advent International and Viking Global led an investment of more than $400 million in 2021 and 2022. Thredd (UK) Ltd's accounts for 2025 show revenue of ~$56M, up 11%, and a loss of ~$50M.
It fits a scaled fintech, neobank or programme manager with engineers and card volumes that justify a processor contract. It is a weaker fit for a small business that wants cards without running a programme, which a programme manager built on Thredd may serve better.
Rating by criterion
Each of the eight criteria below is scored out of 100.
Sector criteria
Thredd processes debit, prepaid and credit cards, physical and virtual, on Visa and Mastercard, with tokens for mobile wallets. It covers issuing only, so card acceptance needs a separate provider.
APIs cover card and account management, and clients can receive real-time authorisation messages and decide approvals themselves. The documentation is public, but integration is a project for an engineering team.
Thredd works as a processor for regulated issuers under card-scheme security rules and offers fraud and 3D Secure tools. The issuer still holds the licence and the compliance duty.
Thredd connects to Visa and Mastercard and works with banks, BIN sponsors and programme managers in the UK, Europe and Asia-Pacific. Ask which sponsors it already works with in the target market.
Vendor criteria
Thredd has entered the US since 2023, and 2025 revenue grew 11%. Losses remain large relative to revenue, so tie any roadmap promise to the contract.
Onboarding is a sales-led implementation with scheme and sponsor set-up. Plan for several months of set-up before a new card programme goes live.
No prices are published. Processing fees are quoted per programme.
Processor contracts are negotiated. Ask about minimum volumes, exit support and how card data moves at the end.
Against its peers
These are the other companies in payments and acquiring, with their ratings.
Fact file
| Legal entity | Thredd (UK) Ltd, company 09926803 |
|---|---|
| 2025 revenue | ~$56M, up 11% |
| 2025 loss | ~$50M |
| Former name | Global Processing Services (GPS) |
| Investors | Advent International and Viking Global, with Temasek and MissionOG |
Competitive landscape
Card issuer processors a fintech or bank would compare with Thredd.
Thredd: 74
- Thredd74
- Tribe Payments71
- Change Financial67
- MarqetaNot reviewed
- PaymentologyNot reviewed
- GalileoNot reviewed
Comparisons
Key leadership
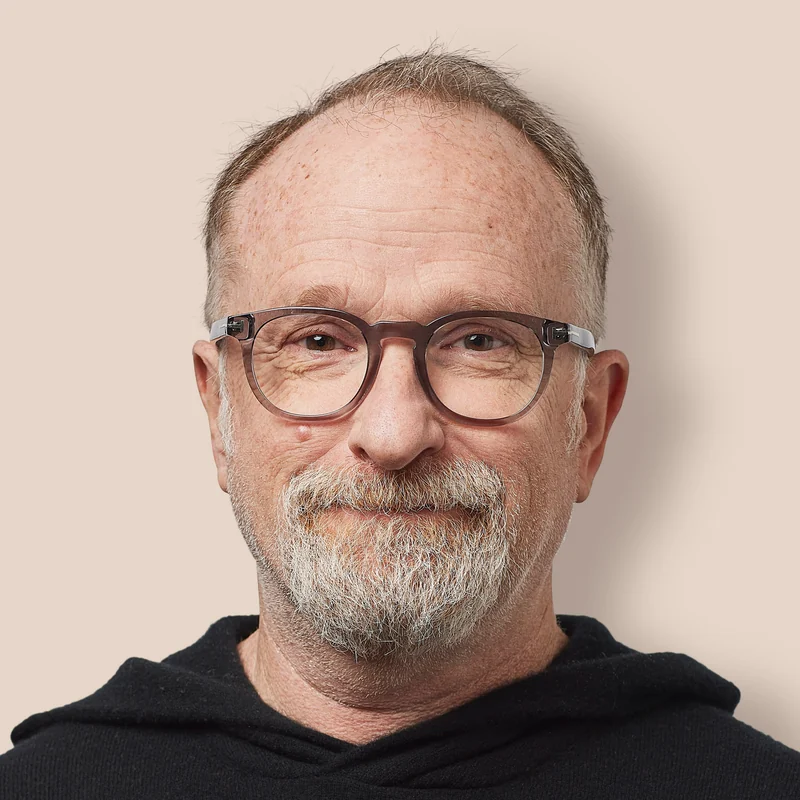
Jim McCarthy has been chief executive since October 2023, after joining that January as head of product and sales.
How this review was created
This profile gives our own assessment of Thredd to companies selecting a Payments & acquiring provider. The Fintech Index receives nothing for featuring a firm, for sponsorship, or for advertising, and Thredd gave us no payment for the profile.
The rating equals the average of eight criteria, with every criterion running from 0 to 100. Four address buyer needs in this sector, and four address the company together with its commercial terms.
Ratings are our editorial judgment, made from public information: pricing and legal pages, product documentation, compliance disclosures, and filings. Fact-checking took place on October 22, 2026.