Fintech Enforcement Action Statistics: 2026 Report
How often does the federal consumer finance watchdog go after fintech companies? We counted every public enforcement action the CFPB has brought since 2012 and read each case page.

The Consumer Financial Protection Bureau (CFPB) can bring enforcement actions against payment apps, digital banks and online lenders that overcharge or mislead their customers. In 2025 it brought far fewer new cases than in earlier years and dropped or ended many older ones, so we counted how its enforcement has changed.
Our analysts studied all 386 public enforcement actions the CFPB has brought since 2012, using the agency's enforcement database and each action's case page as of October 13, 2026. We counted actions by the year they were first filed and flagged those brought against fintech and online lending companies.
In the following sections, we compare actions by year, list the penalties fintech companies have paid, and show the cases the CFPB dropped or ended early in 2025.
CFPB Enforcement Actions per Year
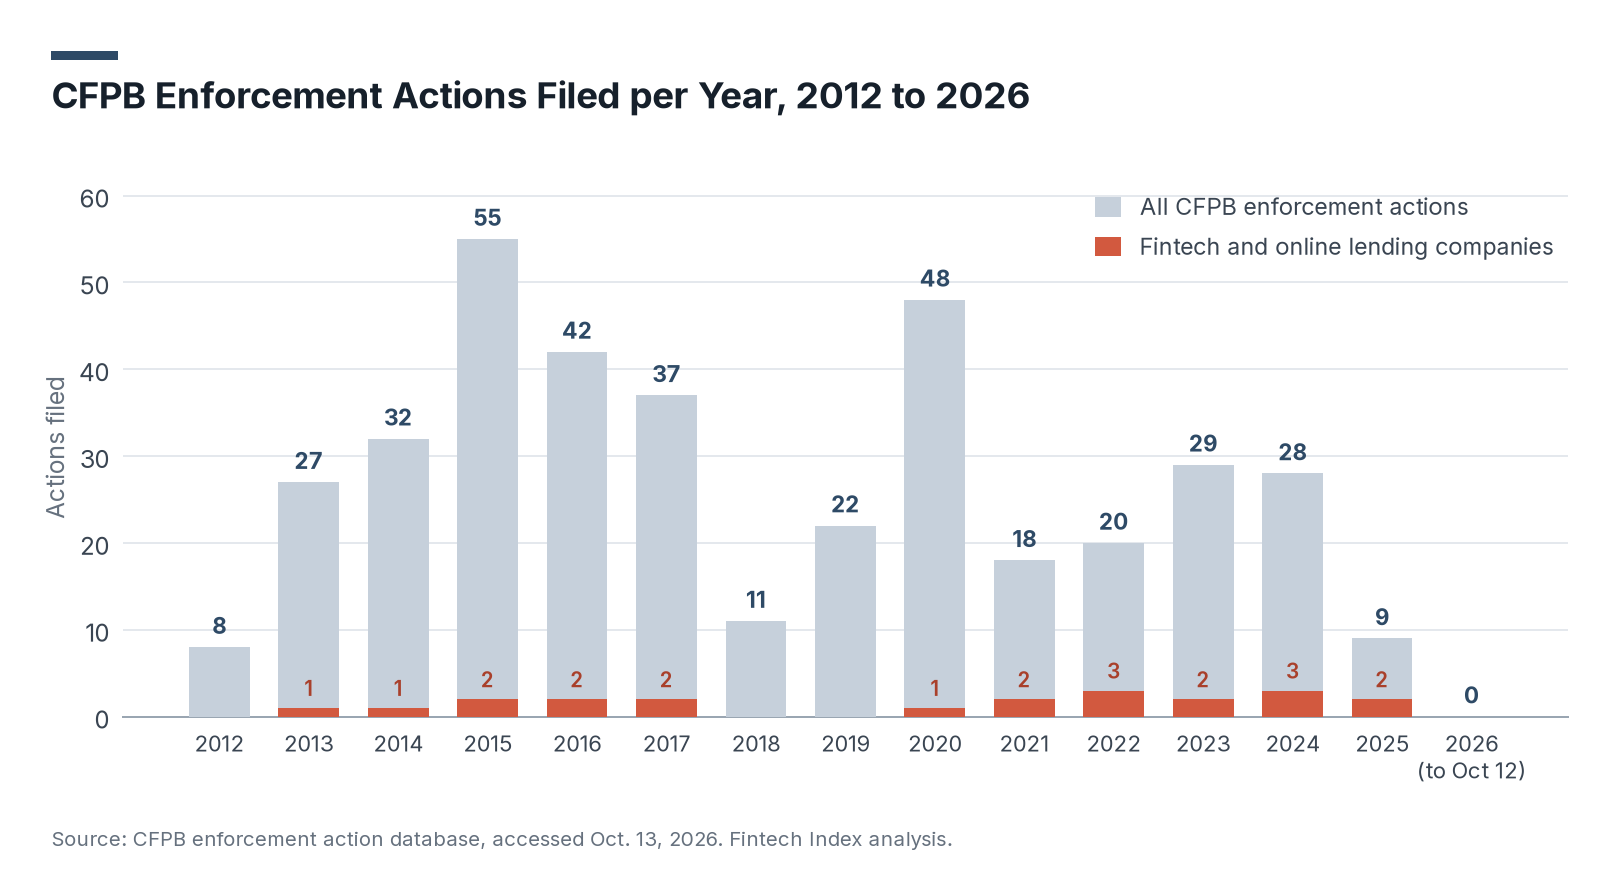
The CFPB lists every public enforcement action it has brought since 2012, by the date the action was first filed. The table counts all actions and those against fintech and online lending companies.
| Year | All Enforcement Actions | Actions Against Fintech and Online Lending Companies |
|---|---|---|
| 2012 | 8 | 0 |
| 2013 | 27 | 1 |
| 2014 | 32 | 1 |
| 2015 | 55 | 2 |
| 2016 | 42 | 2 |
| 2017 | 37 | 2 |
| 2018 | 11 | 0 |
| 2019 | 22 | 0 |
| 2020 | 48 | 1 |
| 2021 | 18 | 2 |
| 2022 | 20 | 3 |
| 2023 | 29 | 2 |
| 2024 | 28 | 3 |
| 2025 | 9 | 2 |
| 2026, through Oct. 12 | 0 | 0 |
| Total | 386 | 21 |
- The CFPB filed 9 enforcement actions in 2025, against an average of 31.0 per year from 2015 to 2024.
- Eight of the 9 actions in 2025 were filed from January 6 to January 30. The only later one, against Synapse Financial Technologies in August 2025, was filed together with a proposed stipulated judgment.
- Fintech and online lending companies account for 21 of the CFPB's 386 actions, or 5.4%.
- New federal cases against fintech companies have nearly stopped. The CFPB has filed no action against any company in 2026, and its only fintech action after January 2025, against Synapse, was filed together with a proposed settlement.
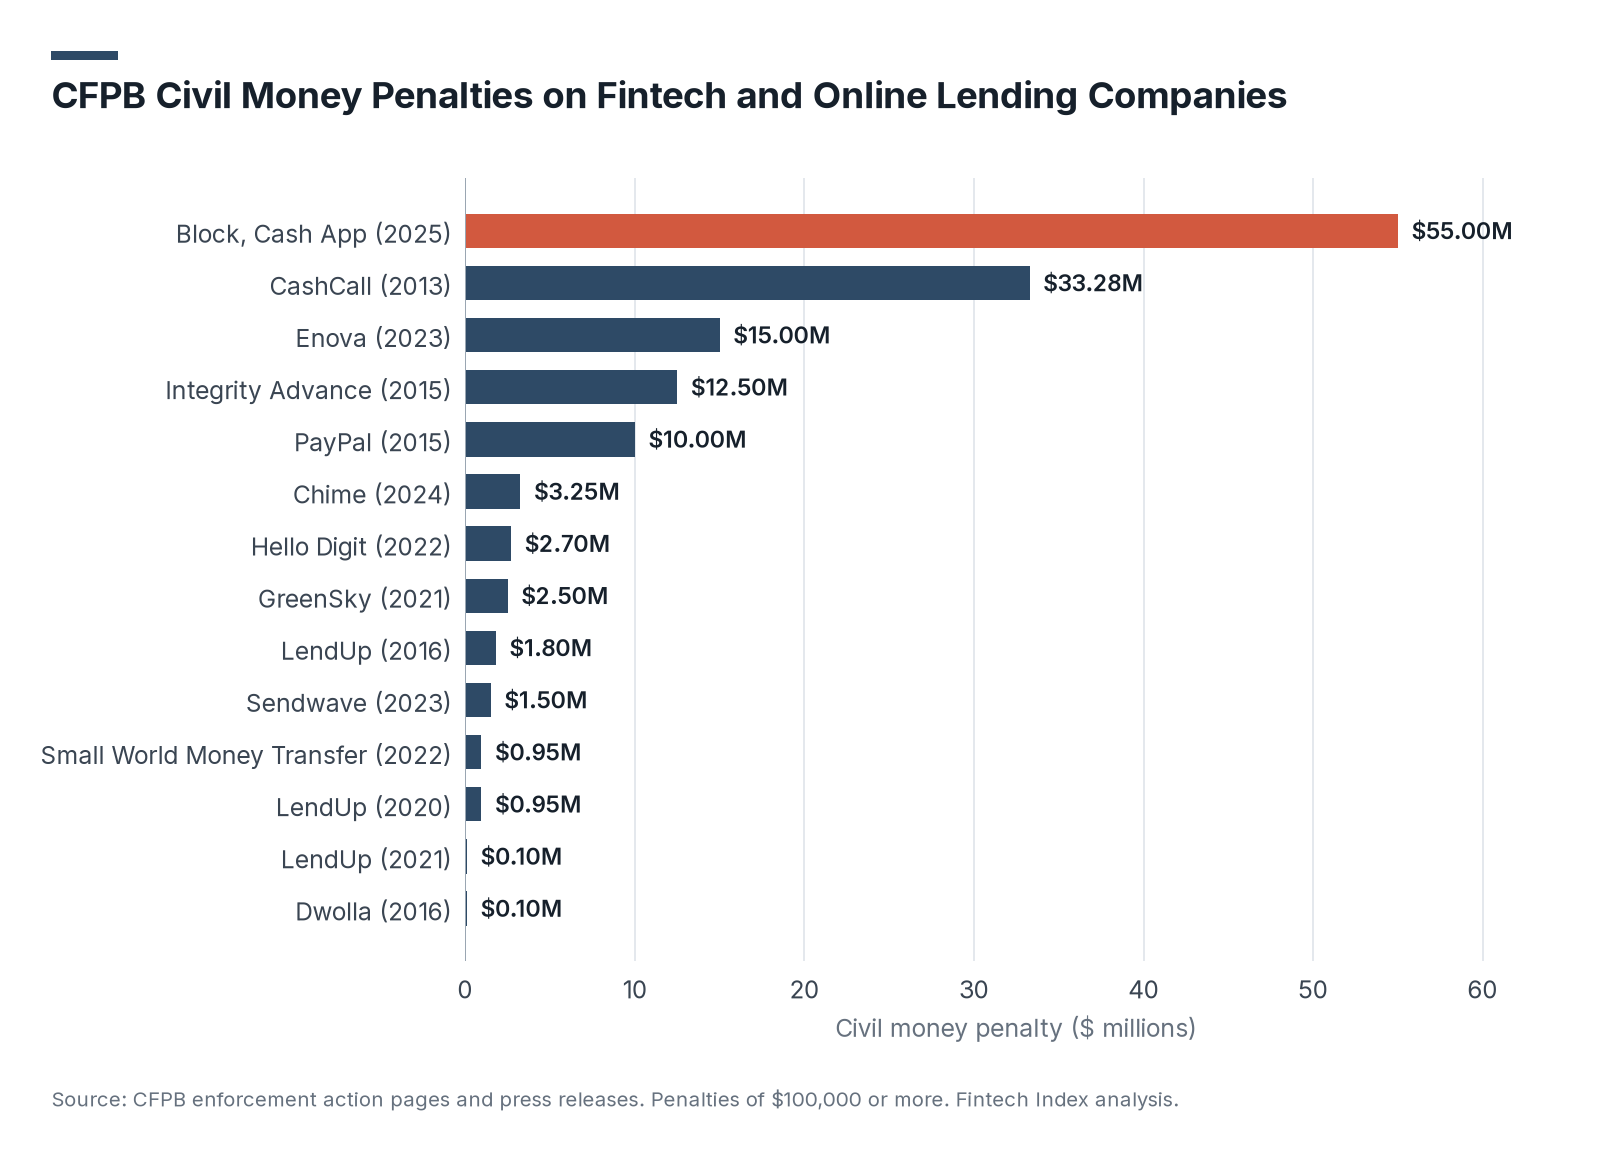
CFPB Civil Money Penalties on Fintech Companies
Civil money penalties are fines paid to the CFPB, separate from refunds and redress paid to consumers. The table lists the penalty and consumer relief stated for each fintech and online lending action.
| Filed | Company | Business | Civil Money Penalty | Consumer Redress Stated | Status |
|---|---|---|---|---|---|
| Jan. 2025 | Block, Inc. (Cash App) | Payment app | $55,000,000 | At least $75 million, up to $120 million | Post order |
| Dec. 2013 | CashCall, Inc. and affiliates | Online loan servicer | $33,276,264 | $134,058,600 restitution | Post judgment |
| Nov. 2023 | Enova International | Online small-dollar lender | $15,000,000 | Not stated | Terminated Sept. 2025 |
| Nov. 2015 | Integrity Advance and its CEO | Online lender | $12,500,000 | More than $38 million restitution | Post judgment |
| May 2015 | PayPal and Bill Me Later | Online credit | $10,000,000 | $15,000,000 | Post judgment |
| May 2024 | Chime Financial | Digital banking accounts | $3,250,000 | At least $1.3 million | Post order |
| Aug. 2022 | Hello Digit | Automated savings app | $2,700,000 | At least $68,145 | Post order |
| July 2021 | GreenSky | Point-of-sale lending platform | $2,500,000 | Up to $9 million | Post order |
| Sept. 2016 | LendUp (Flurish) | Online lender | $1,800,000 | About $1.83 million | Post order |
| Oct. 2023 | Sendwave (Chime, Inc.) | Remittance app | $1,500,000 | About $1.5 million | Post order |
| Oct. 2022 | Small World Money Transfer | Remittance app and website | $950,000 | Not stated | Post order |
| Dec. 2020 | LendUp Loans | Online lender | $950,000 | $300,000 | Post order |
| Sept. 2021 | LendUp Loans | Online lender | $100,000 | $40.5 million, suspended | Post order |
| Mar. 2016 | Dwolla | Online payment platform | $100,000 | Not stated | Expired |
| Nov. 2017 | Think Finance | Online installment loans | $7 | Not stated | Post order |
| Aug. 2025 | Synapse Financial Technologies | Banking-as-a-service provider | $1 | Not stated | Pending |
| Sept. 2022 | MoneyLion Technologies | Fintech lender | None | $1.75 million | Post judgment |
| Sept. 2014 | Hydra Group (SSM Group and others) | Online payday lender | None | $69 million judgment, limited by ability to pay | Post judgment |
| Apr. 2017 | Golden Valley Lending and three others | Online lenders | None | None | Dismissed |
| May 2024 | SoLo Funds | Peer-to-peer lending app | None | None | Dismissed Feb. 2025 |
| Dec. 2024 | Walmart and Branch Messenger | Earned wage payments app | None | None | Dismissed May 2025 |
- Civil money penalties against fintech and online lending companies total $139,626,272 across the 21 actions.
- Block's $55 million penalty in January 2025 is 39.4% of that total and the largest of any action in this group.
- Large CFPB fines against fintech companies have been rare. Only five of the 21 actions carried a penalty of $10 million or more, and five carried no penalty at all.
CFPB Enforcement Actions Dismissed or Terminated in 2025
In 2025, the CFPB dropped a series of pending lawsuits and ended many consent orders early. The action pages record each dismissal or termination and its date.
- At least 39 earlier enforcement actions were voluntarily dismissed, terminated early or vacated in 2025, according to the CFPB's own action pages.
- They include the lawsuits against Capital One, Early Warning Services (operator of Zelle) with Bank of America, JPMorgan Chase and Wells Fargo, and Rocket Homes, all dismissed from February to March 2025.
- From May to November 2025, the CFPB also terminated at least 17 consent orders early, including orders against Apple, Bank of America, Citibank and Navy Federal Credit Union. Most of those termination notices say the CFPB waived any alleged non-compliance with the order.
- Three were fintech actions: SoLo Funds, dismissed on February 21, 2025; Walmart and Branch Messenger, dismissed on May 13, 2025; and Enova, whose 2023 order was terminated on September 2, 2025.
- A lawsuit against Snap Finance was also dismissed with prejudice on May 27, 2025.
- The CFPB withdrew as a plaintiff in April 2025 from two cases it had brought alongside state attorneys general, against MoneyGram and Credit Acceptance, and dismissals continued in 2026, including the case against Colony Ridge in February.
- A CFPB order is not lasting protection for consumers. Orders already in place were ended years ahead of schedule in 2025, often with the agency waiving any claim that the company had failed to comply.
The agency's own funding has also been in dispute. In November 2025, the Justice Department's Office of Legal Counsel concluded that the CFPB could draw money from the Federal Reserve only out of the Fed's profits, and the CFPB's acting director declined to request any funds for fiscal 2026. Twenty-two states and the District of Columbia sued, and three federal district courts have since rejected that reading, most recently in Oregon on September 25, 2026; two of those rulings are on appeal. A House bill voted out of the Financial Services Committee would instead fund the CFPB through the annual congressional appropriations process.
What Fintech Enforcement Action Trends Mean for 2027 and Beyond
The federal agency that used to take payment apps and online lenders to court on customers' behalf has largely stepped back. Fewer new cases means fewer orders that send refunds to customers who were overcharged or misled, and some of the orders already in place have been lifted, so part of the protection those customers had is gone.
That could change. Courts have ordered the agency to keep asking the Federal Reserve for the money it needs to operate, while Congress weighs a bill that would put its budget to a yearly vote. Whether the agency goes back to bringing cases, or loses the money to bring them, decides how much protection fintech customers get from the federal government and how much of that work falls to the states.
So if a fintech app or online lender treats you unfairly, file a complaint with your state's financial regulator or attorney general as well as with the CFPB.
Data Collection and Methodology
The Fintech Index research team collected all 386 enforcement actions shown in the CFPB's public enforcement database as of October 13, 2026, along with each action's detail page.
Actions are counted in the year of the initial filing date the CFPB lists. An action is classified as a fintech and online lending action when the CFPB's own description of the company uses terms such as "financial technology", "fintech", "online lender", "online loans", "online credit", "online payment", "mobile application" or "peer-to-peer", and the company is not a bank or credit union. This rule leaves out some companies often described as fintech, such as Wise US and Snap Finance, whose action pages do not use those terms; all 386 actions and their classification are in data.csv. Civil money penalties and redress are the amounts stated on each action page, or in the CFPB press release for PayPal, and are not adjusted for later modifications or for amounts collected. Integrity Advance's figure combines a $7.5 million penalty on the company and $5 million on its CEO. Dismissals and terminations in 2025 were identified by reading the dated entries on each action page, including orders the CFPB terminated early under 12 U.S.C. § 5563(b)(3), and exclude rulings that only narrowed a case and withdrawals from cases brought with state attorneys general. Because the count depends on how each page describes the event, it is a minimum.
This report covers CFPB actions only. Enforcement against fintech companies by FinCEN, the OCC, the SEC and state regulators is not included.
Sources
- Fintech Index, Fintech Enforcement Study: analysis of all 386 CFPB public enforcement actions filed from 2012 to October 12, 2026, conducted October 2026.
- CFPB, Enforcement Actions
- CFPB, Enforcement action definitions
- CFPB, Block, Inc. enforcement action
- CFPB, Synapse Financial Technologies, Inc. enforcement action
- CFPB, press release on PayPal, May 19, 2015
- CFPB, Civil Penalty Fund
- CFPB, Enova International, Inc. (2023) enforcement action
- CFPB, Apple Inc. enforcement action
- Goodwin, Court Vacates CFPB Director's Bid to Zero Out Funds, October 12, 2026
- U.S. District Court for the District of Oregon, State of New York v. Vought, opinion of September 25, 2026